A monthly energy bill can show a cost increase, but it rarely explains which production line, site, vehicle run or process created the change. That gap is where emissions reporting becomes difficult for operational businesses. The numbers are often available, yet they sit across invoices, meter reads, fuel cards, production records, supplier documents and spreadsheets that do not reconcile easily.
For manufacturers, processors, warehouses, plantations and labour-hire businesses, credible reporting starts with the way work is actually done. It requires a clear connection between operational activity and financial records, not a separate exercise completed at year end. When teams can trace emissions data back to source transactions, they gain more than a compliance report. They can see where energy, fuel, materials and waste are affecting margin, planning and customer commitments.
Why emissions reporting belongs in the operating system
Carbon reporting is sometimes treated as a sustainability project owned by one person or an external adviser. That approach can work for a small, simple organisation with limited sites and straightforward energy use. It becomes unreliable when a business runs multiple locations, carries stock, operates machinery, sends goods through a transport network or works with a broad supplier base.
The operational team knows what happened. Finance knows what was purchased and paid for. Maintenance may hold machine runtime data, while procurement manages supplier information. If each team maintains a different version of the data, the reporting process becomes a long hunt for evidence. It also makes it hard to answer reasonable questions from directors, customers or auditors about how a figure was calculated.
A connected ERP platform changes the starting point. Purchase invoices, inventory movements, production orders, labour records, utility bills and project costs can be held in one controlled environment. Carbon accounting can then use the same transactions that already support financial reporting and operational management. This reduces duplicate data entry and gives teams a more dependable audit trail.
The aim is not to pretend every number is perfect from day one. It is to establish a repeatable process where assumptions are visible, source data is retained and improvements can be made each reporting cycle.
Build emissions reporting around clear boundaries
Before choosing dashboards or calculating totals, define what the report covers. A business may report by legal entity, site, operating division, contract or product line. The right boundary depends on the purpose of the report, the organisation’s structure and the information requested by customers, financiers or regulators.
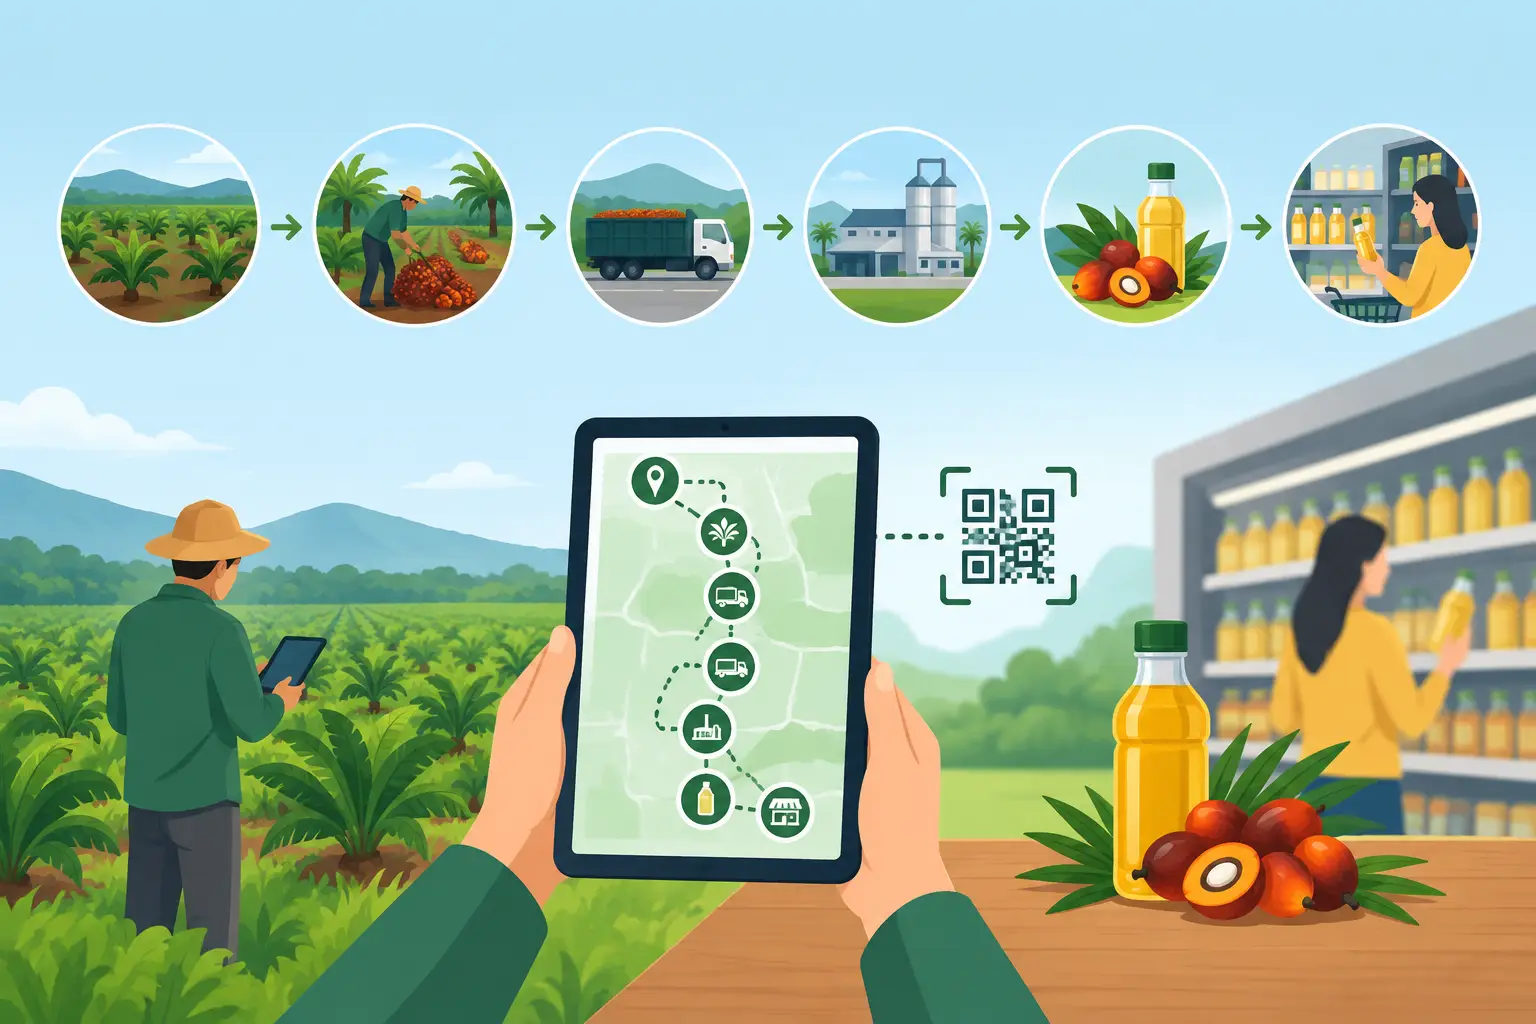
Start by documenting the sites, assets and activities included. For example, a food processor may include its factory, cold storage, company vehicles and gas-fired equipment, while recording third-party freight separately. A plantation business may need to distinguish emissions associated with irrigation pumps, fertiliser use, field operations and packing facilities. Clear boundaries prevent double counting and make year-on-year comparisons more meaningful.
Most frameworks group emissions into three broad categories. Scope 1 covers direct emissions from sources the business owns or controls, such as fuel used in vehicles or onsite gas. Scope 2 generally relates to purchased electricity and other acquired energy. Scope 3 covers indirect value-chain emissions, including purchased goods, transport providers, waste and business travel.
Scope 3 is often the largest and least precise category. It should not be ignored simply because supplier data is incomplete, but it should be handled honestly. Estimates based on spend, distance, weight or industry factors may be appropriate at first. The report should identify where estimates were used, which factor was applied and what evidence would improve the calculation next time.
Choose material data, not every possible data point
Trying to capture every minor source immediately can stall the entire program. Focus first on activities that are material to emissions, cost or customer requirements. For an industrial garment washing operation, electricity, gas, water heating and chemical use are likely priorities. For a labour-hire business, travel, office energy and subcontractor arrangements may matter more than production machinery.
Materiality is not a reason to exclude inconvenient data. It is a practical way to sequence the work. Once the largest sources are controlled, teams can extend coverage with greater confidence.
Turn daily transactions into usable carbon data
A reporting model is only as useful as its source data. The most effective setup captures activity close to where it occurs, then applies consistent conversion factors and calculation rules. This is where a cloud ERP can connect financial control with day-to-day operations.
For energy and fuel, retain the invoice, billing period, unit of measure and site or cost centre. If a facility has sub-metering, allocate usage to the relevant production area or department where practical. Machine and PLC integration can add another layer of insight by recording runtime, throughput, temperature cycles or energy consumption from connected equipment. This helps teams investigate why emissions per unit have changed, rather than simply observing that the total has risen.
Inventory and purchasing records also matter. A well-structured item master can identify materials, packaging and consumables with relevant environmental attributes. Supplier records can hold supporting declarations, transport details or agreed data formats. Production recipes and bills of materials can then connect input consumption to batches, work orders or finished products.
The key is sensible configuration. Not every stock item needs a detailed emissions profile, and not every supplier can provide primary data. Begin with the materials and vendors that have the greatest volume, cost or customer relevance. Build the process so better data can replace broad estimates without redesigning the entire reporting model.
Make finance part of the control process
Emissions data needs the same discipline as financial data. If utility invoices are missing, fuel transactions are coded inconsistently or production quantities are adjusted without explanation, carbon results will be unreliable. Finance teams are well placed to establish controls because they already manage approvals, coding structures, period close and supporting documents.
Useful controls include mandatory site or cost-centre fields for energy and fuel purchases, approved units of measure, locked reporting periods and a documented review of large movements. An unexplained rise in electricity emissions may be a genuine operational event, such as extra shifts or refrigeration demand. It may also be an invoice entered twice, a meter read covering an unusual period or a unit conversion error. The review process should distinguish between these possibilities before results are published.
A monthly reporting cadence is usually more useful than an annual scramble. Monthly data allows operations leaders to compare energy and fuel use with production volume, labour hours, revenue, hectares harvested or tonnes dispatched. The appropriate intensity metric depends on the business. A warehouse may track emissions per order shipped, while a manufacturer may track emissions per unit, batch or tonne produced.
Power BI dashboards can make these patterns visible to people who need to act on them. However, a dashboard should show the source and confidence behind the number, not just a headline total. Leaders need to know whether a result is based on invoices, meter data, supplier information or an estimate.
Use reporting to improve operational decisions
The commercial value of emissions reporting comes from using it in decisions. When data is linked to operational drivers, managers can test practical questions: Is a new production schedule reducing energy per unit? Which site has the highest fuel use per delivery? Has a change in packaging increased material intensity? Are higher utility costs caused by volume growth or declining efficiency?
This does not mean every decision should be based on carbon alone. A lower-emissions option may have a longer lead time, higher purchase cost or a quality risk. The right choice depends on customer requirements, available capital, safety, production capacity and commercial margin. Good reporting makes the trade-offs visible so they can be assessed deliberately.
OneBusiness can support this approach by bringing carbon accounting, finance, inventory, production, project and machine data into one configurable cloud platform. For operationally complex businesses, that means emissions information can sit alongside the records teams already use to plan work, control costs and manage performance.
Prepare for questions before they arrive
Customers and larger supply-chain partners increasingly ask businesses for emissions information. The request may be broad at first, then become more specific as procurement standards mature. A team that can provide a clear methodology, reporting boundary, source evidence and explanation of estimates is in a stronger position than one that only has a final spreadsheet total.
Keep a calculation register that records emission factors, data sources, units, assumptions and any changes from the previous period. Store evidence with the related transaction where possible. When a factor changes or supplier-specific data becomes available, document the effective date and impact. This creates continuity even when staff move roles or an external reviewer becomes involved.
The best next step is usually modest: choose one site, one reporting period and the largest sources of energy, fuel or materials. Build a process that your finance and operations teams can run together, then improve its coverage and precision over time. A report that is traceable, timely and useful to the people running the business is far more valuable than a polished figure nobody can explain.