A warehouse can look orderly while its stock records are quietly drifting away from reality. A carton is put away in the wrong bay, materials are issued to production without being scanned, or a receiving quantity is entered incorrectly. Small errors compound into delayed orders, unexpected purchasing and difficult month-end reconciliations. So, what is inventory cycle counting? It is a planned process of counting selected inventory items regularly throughout the year, then investigating and correcting differences between the physical count and the system record.
Unlike a full stocktake, cycle counting does not require the entire warehouse or shop floor to stop. Teams count a manageable group of items each day, week or month while normal operations continue. For businesses with active warehouses, production stores, retail locations or multiple stock points, that continuity is often the main advantage.
What Is Inventory Cycle Counting and Why Use It?
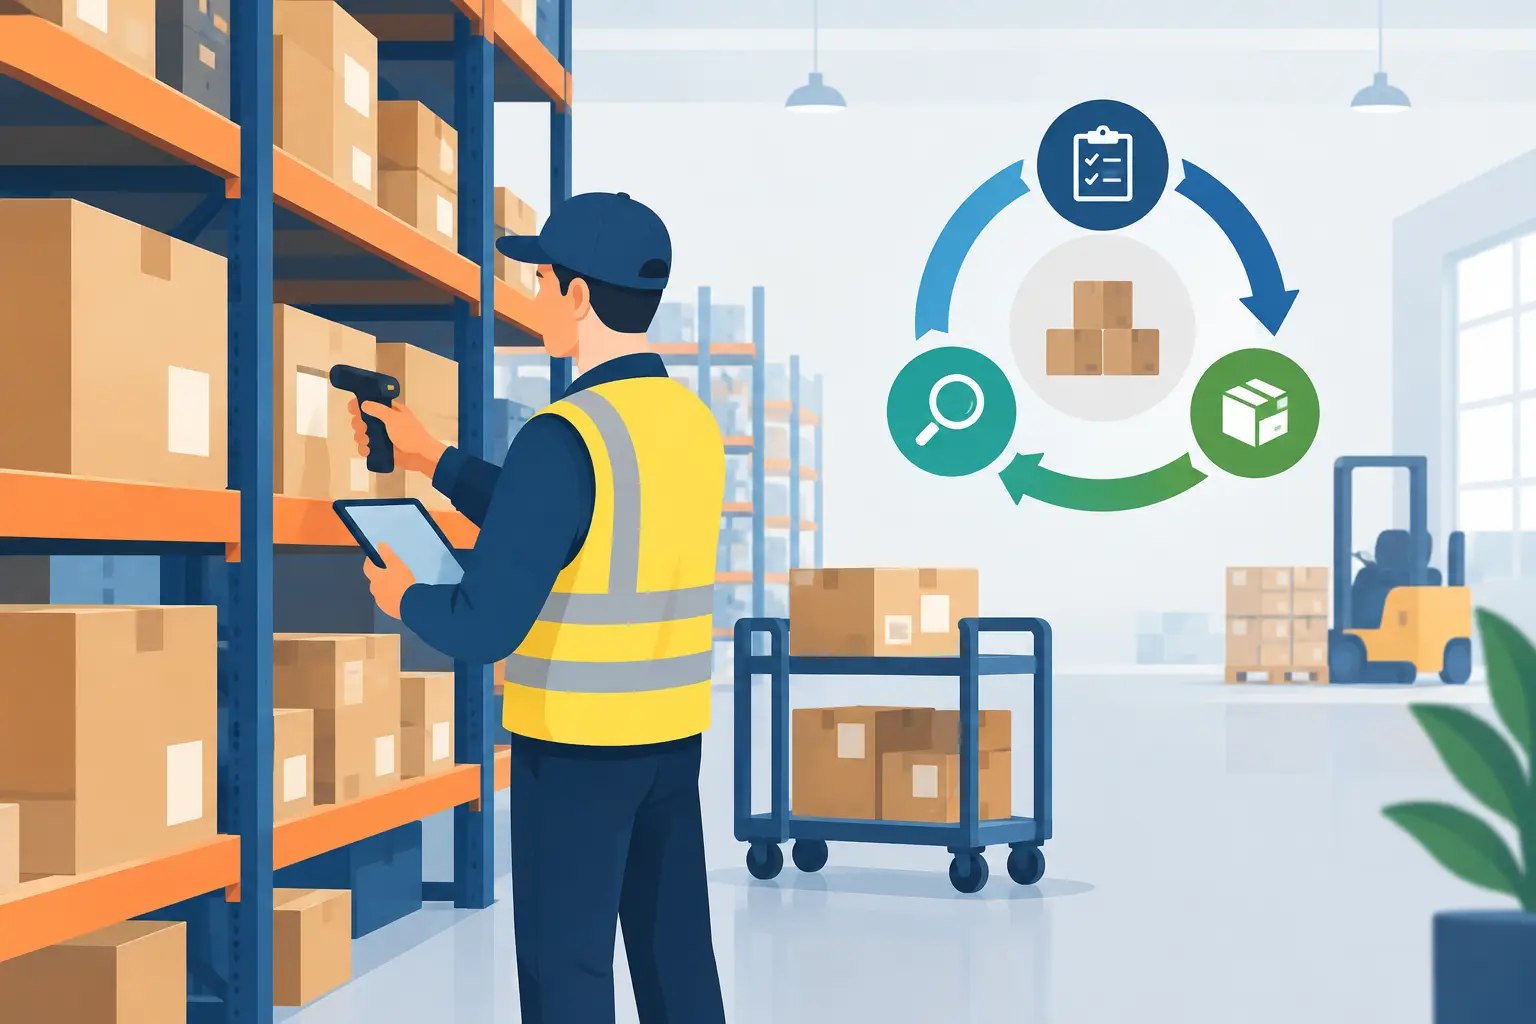
Inventory cycle counting is a continuous inventory control method. Rather than checking every item once or twice a year, a business divides its inventory into count groups and works through them on a repeating schedule. The system records expected quantities, the counter verifies what is physically available, and any variance is reviewed before an adjustment is posted.
The purpose is not simply to make the inventory balance look tidy. It is to improve confidence in the data used for purchasing, production planning, sales commitments, financial reporting and replenishment. If a system says there are 500 units of a component available, planners need to know whether that number can be trusted before scheduling a production run.
Regular counts also surface process problems earlier. A repeated shortage in one location may point to poor bin discipline, unrecorded scrap, inaccurate units of measure, receiving errors or stock being moved without a transaction. Treating every variance as a simple adjustment misses the operational insight cycle counting can provide.
Cycle Counting Versus a Full Stocktake
A full stocktake aims to verify all inventory at a particular point in time. It is often required for financial reporting and can be useful after a major system change, warehouse relocation or serious control issue. However, it can be disruptive. Teams may need to pause dispatches, production consumption and receipting to prevent stock moving while it is counted.
Cycle counting spreads that workload across the year. It reduces the scale of any one counting event and makes discrepancies more visible while the related transaction is still relatively recent. A manufacturing business, for example, can count high-value raw materials each week, work-in-progress locations fortnightly and lower-value packaging items less often.
It depends on the business whether cycle counting can replace an annual wall-to-wall count for every reporting purpose. Auditors, insurers, internal controls and industry requirements may still call for a full verification. Even so, a disciplined cycle count program makes the annual exercise faster, less disruptive and less likely to produce surprises.
Which Stock Should Be Counted Most Often?
The best count schedule is driven by risk, value and movement, not by a rule that every SKU deserves equal attention. ABC analysis is a common starting point. A-items are high-value, high-volume or operationally critical products and materials. B-items are moderately important, while C-items are lower-value or slower-moving stock.
A-items may be counted weekly or monthly. C-items might only need a quarterly or annual count. But value is not the only consideration. A low-cost gasket that stops a production line when unavailable can deserve frequent checks. So can fast-moving retail stock, controlled materials, seasonal products, items with a history of variances, and goods held across several locations.
For process manufacturers, the counting model may need to include bulk tanks, batches, yields, by-products and material losses. Plantations may need to reconcile harvested output, field transfers and packhouse inventory. Labour-hire and service businesses may focus less on saleable stock but still need reliable control of consumables, equipment and assets assigned across sites.
A Practical Inventory Cycle Counting Process
A reliable process combines clear warehouse discipline with system controls. The steps are straightforward, but the detail matters.
- Set the count plan. Define which items and locations will be counted, how often, and who is responsible. Use item value, velocity, criticality and previous accuracy to prioritise the schedule.
- Prepare the location. Where possible, complete or pause movements in the area being counted. Label bins clearly and separate damaged, quarantined, returned and unprocessed goods from available stock.
- Count without bias. Give the counter a count task or blind count sheet that does not show the expected quantity. This reduces the risk of someone counting towards the system figure instead of recording what is physically there.
- Review variances. Recount material differences and check recent receipts, picks, transfers, production issues, returns and unit-of-measure conversions. The person approving an adjustment should understand the reason, not just the numerical gap.
- Post corrections and improve the process. Update the inventory record with an audit trail, then assign corrective actions where patterns appear. That might mean retraining, relabelling locations, changing approval rules or improving barcode scanning.
For high-risk items, independent recounts and supervisor approval are sensible safeguards. In smaller operations, one person may wear several hats, but no single employee should be able to count, approve and adjust stock without oversight.
What Good Cycle Count Accuracy Looks Like
Inventory accuracy is commonly measured by comparing correctly recorded items with the total items counted. A business might also measure quantity accuracy, value of adjustments, frequency of recounts and the age of unresolved variances. The right target varies by industry and stock profile, but the trend matters as much as the headline percentage.
An apparently strong accuracy rate can hide a serious issue if the errors sit in critical materials. If 98 per cent of low-value items are correct but a key production ingredient is repeatedly short, the operation still faces planning and customer-service risk. Reports should therefore show accuracy by warehouse, item class, location, supplier, product family and reason code.
Finance teams should also monitor the value and cause of write-offs. Inventory adjustments affect cost of goods sold, margins and working capital. Frequent unexplained corrections can indicate control weaknesses, but they can also reveal a genuine process issue such as incorrect bill of materials quantities or unrecorded production waste.
Common Reasons Cycle Counts Fail
Cycle counting becomes ineffective when it is treated as an occasional clean-up task. Counting only when a problem is suspected creates a reactive program and gives management little visibility into the true condition of stock records.
Another common issue is counting the item but ignoring the location. A system may show the correct total quantity across a warehouse, yet the stock is in the wrong bin or unavailable to the picker. For multi-site businesses, the same problem can occur between branches, production areas and third-party storage locations.
Technology can help, but it does not fix weak procedures by itself. Barcode scanners, mobile warehouse tasks, batch and serial tracking, and automated replenishment reduce manual entry points. They still depend on staff recording movements at the time they happen. If stock transfers are completed later from memory, the system will remain behind the physical operation.
How an ERP Strengthens Inventory Cycle Counting
A connected ERP system makes cycle counting more than a warehouse activity. It can generate count tasks based on item class and risk, restrict movements in selected locations, capture counts on mobile devices and preserve a full adjustment history. Warehouse teams see current stock by bin, batch, serial number or status, while finance teams see the valuation impact in the same system.
For operationally complex businesses, integration matters. When production issues, machine data, sales orders, purchase receipts and warehouse transfers all update one platform, there are fewer handoffs where stock data can be lost. Power BI reporting can then highlight recurring variances, slow-moving stock, negative inventory and locations that need attention.
OneBusiness supports this connected approach by bringing inventory, purchasing, production, accounting and reporting together in one configurable cloud platform. The practical goal is simple: give teams current information they can act on, rather than asking them to reconcile disconnected spreadsheets after the fact.
Start with a count schedule your team can sustain, measure the reasons behind every meaningful variance, and improve the transaction that caused it. Over time, cycle counting becomes a quiet but valuable operating discipline: one that protects cash, supports reliable fulfilment and gives every department greater confidence in the numbers they use each day.